Dollar strength is the dominant thread today: the Fed's 25bp cut on Sept 17 and the BOJ's hike to 1.25% on Sept 18 (seen as less hawkish than feared) have left EUR/USD pinned near multi–month lows, while oil extends its slide on Iran diplomacy hopes.
🌏 Asian Markets
Hang Seng +1.18% to 25,043, Shanghai Composite +0.82% – both closed higher Monday on tech and AI–infrastructure optimism. Tokyo remains shut for Respect for the Aged Day through Wednesday; last Nikkei close was 65,019 (+1.38%) Friday, fueled by chip stocks after the BOJ decision.
💵 EUR/USD
1.1475, –0.09% – euro sits near its weakest since late July as the dollar holds its post–Fed gains.
🥇 Gold (XAU/USD)
~$4,346 – little changed, consolidating after last week's pullback as markets reassess the pace of further Fed easing.
🛢️ Brent Crude
~$100.50, sliding toward its lowest since Sept 10 – pressured by hopes for US–Iran diplomatic movement around the UN General Assembly and a sharp rebound in Saudi export flows through the Strait of Hormuz.
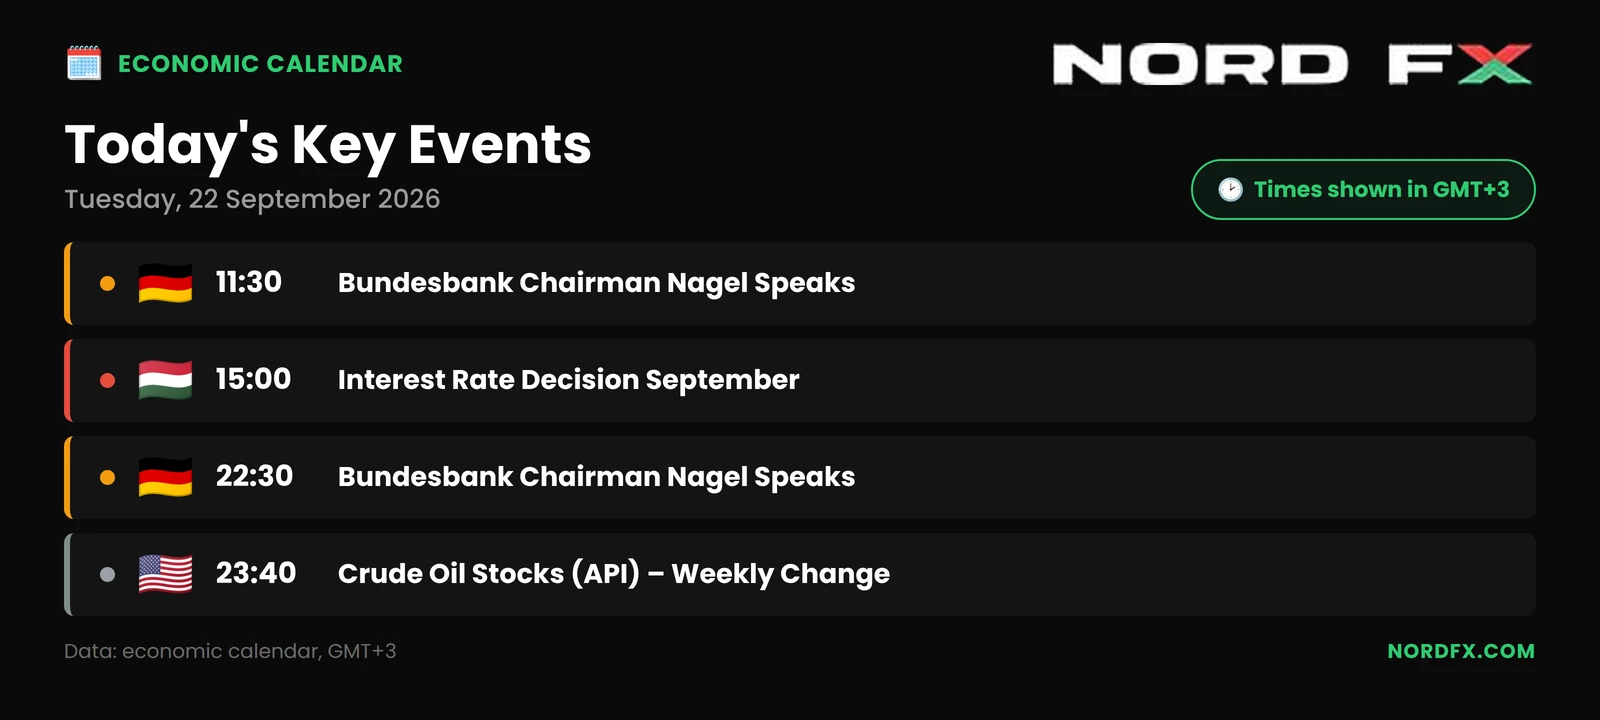
📌 Watch today: any UN General Assembly headlines on Iran, and follow–through in the dollar after the Fed/BOJ divergence.
Go Back Go Back
