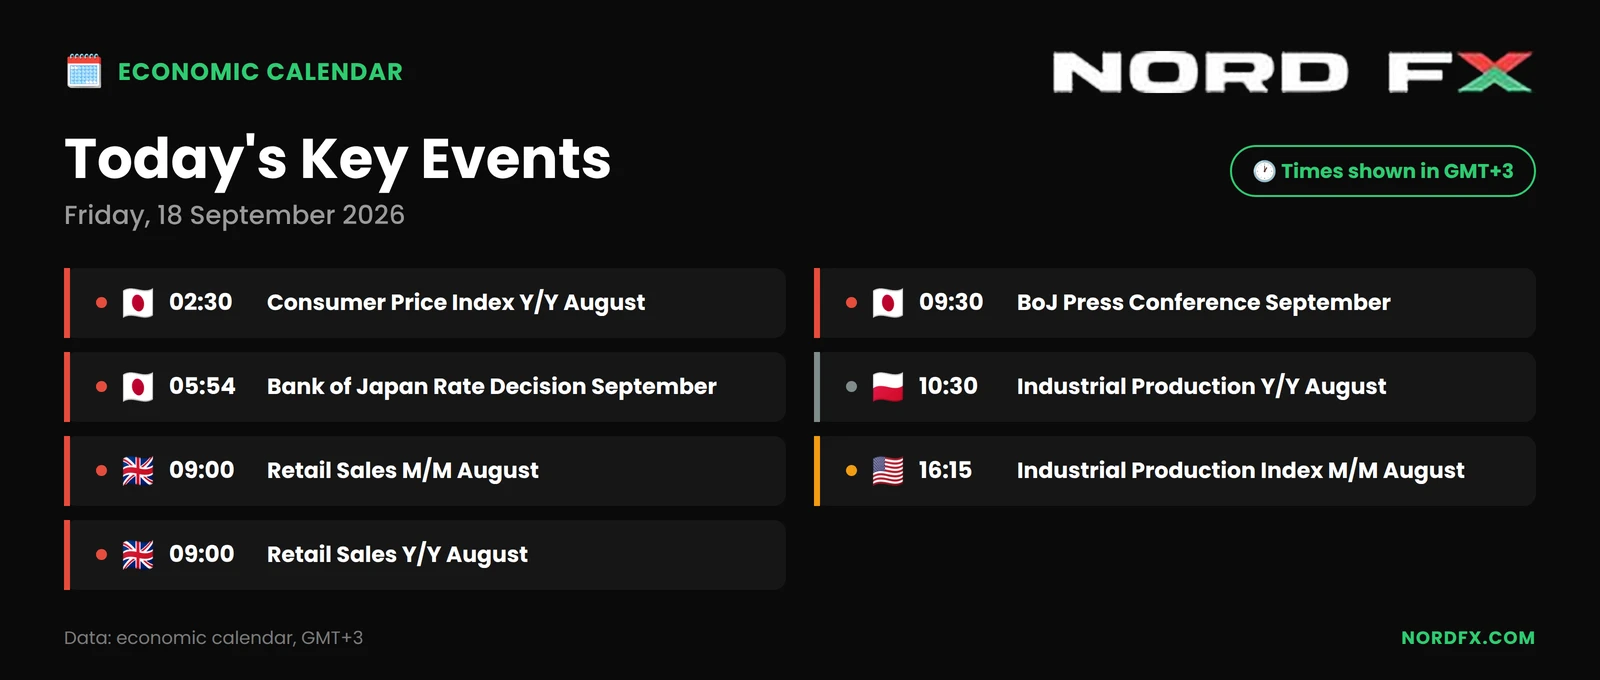
🏛️ Two central banks in focus this week. The Fed hiked 25bp to 3.75%–4.00% on Wednesday – first hike since 2023 – on a "too sticky" inflation picture; one more hike is pencilled in for this year. Stocks slipped on the day (S&P 500 -0.5%, Dow -1.2%).
🇯🇵 This morning the BOJ followed suit, raising its policy rate 25bp to 1.25% – a 31-year high and first hike since June. Governor Ueda cited energy-driven inflation above target, wage pressure from Japan's shrinking workforce, and the need to keep pace with the Fed to limit yen weakness. USD/JPY eased -0.5% to 155.45 as the yen firmed.
🛢️ Brent extended its slide, down 1.1% to $103.62, as Saudi Arabia moves to restore ~half its damaged pipeline capacity within days and reroutes exports via the Strait of Hormuz – easing Middle East supply fears.
🥇🥈 Precious metals are riding the calmer-oil, softer-yields wave: Gold +0.3% to $4,355.70, Silver +1.1% to $65.93 – both near recent highs.
💶 EUR/USD holds at 1.1489 (+0.2%).
₿ Bitcoin is up 0.8% to ~$76,500, holding above $76K.
🌏 Asia rallied on the BOJ move and fading oil-supply risk: Nikkei 225 +1.8% to 65,290 (SoftBank, Advantest and other AI/tech names leading), Hang Seng +0.7% to 24,773 on tech gains (Z.AI, MiniMax) and softer US yields.
⚡ Key theme: a hawkish Fed-BOJ combo against fading Middle East supply risk – watch USD/JPY and oil for the next directional cue.
Go Back Go Back
