🌐 Macro in focus
Bond yields still set the tone. The US 10-year is at 5.24% and the 30-year at 5.56%, both easing today after the 30-year hit its highest since 2002 this week. 📈
US data is weakening: Conference Board consumer confidence fell to 81.9 (lowest since 2014) and JOLTS job openings dropped to 7.08M. Inflation and debt-supply worries are outweighing growth fears. ⚠️
US–Iran talks have made little progress, keeping oil elevated. 🛢
🌏 Asian markets
🇯🇵 Nikkei 225: +2.0% to 66,826 (USD/JPY 157.14)
🇰🇷 KOSPI: –0.4% to 6,843
🇨🇳 Shanghai Composite: +0.3% to 3,840
🇭🇰 Hang Seng: –0.2% to 24,472
🇨🇳 China's official PMIs moved back into expansion: manufacturing 50.1, non-manufacturing 50.2 ✅
🇦🇺 RBA hiked to 4.60% yesterday. Australian CPI came in at 4.0% y/y.
🇺🇸 Wall Street (Tuesday close)
S&P 500: 7,670.84 (–0.17%)
Dow: 51,349.92 (–0.26%)
Nasdaq: 26,797.54 (–0.09%)
S&P 500 futures are +0.3% this morning. 🔼
💱 Markets snapshot
💶 EUR/USD: 1.1332
🥇 Gold: $4,180
🛢 Brent: $96.4
₿ Bitcoin: $83.4K
Ξ Ethereum: $2,674
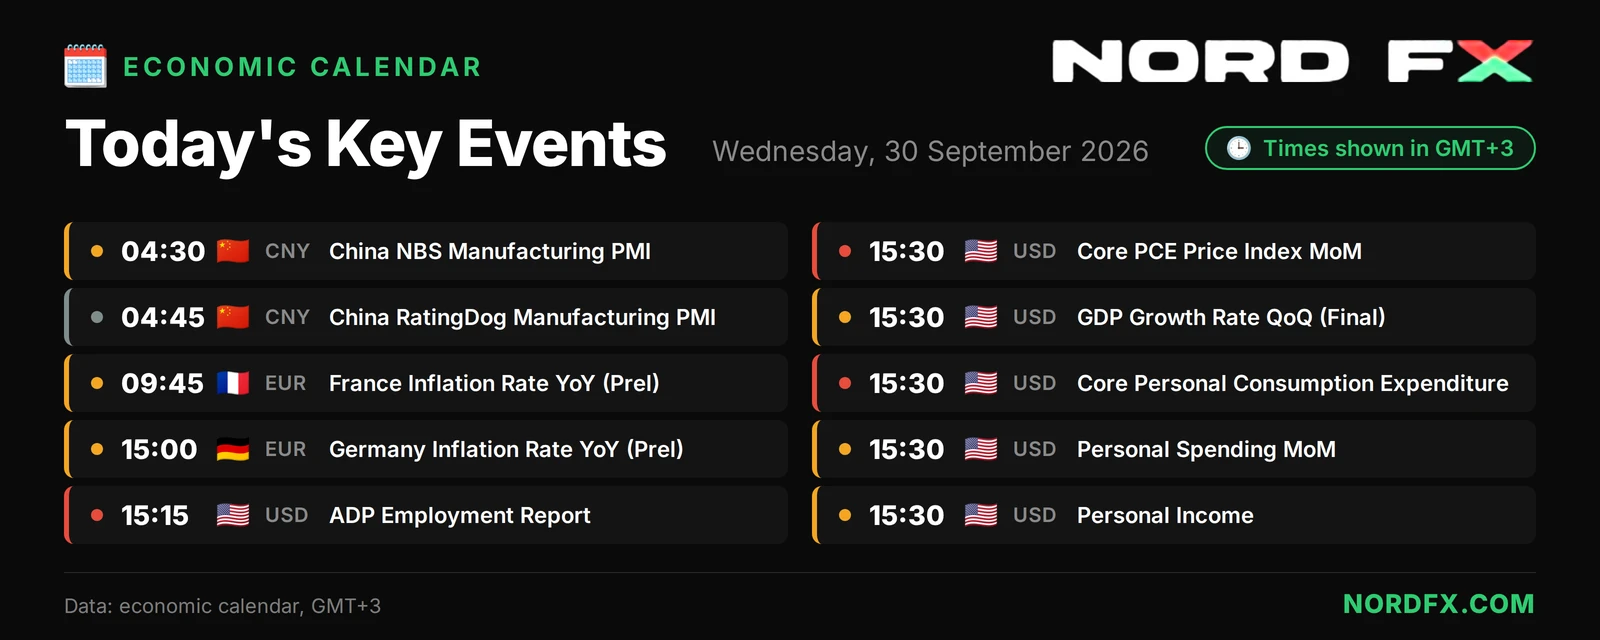
📅 Today
🇺🇸 US PCE inflation (August) at 15:30 GMT+3. The Cleveland Fed nowcast points to about 3.8% headline and 3.4% core.
Later this week: ISM Manufacturing on Thursday and Nonfarm Payrolls on Friday. 👀
Kembali Kembali
