📉 Macro in focus
Weak US jobs data keeps the Fed debate alive. September payrolls came in at just +29K (forecast +90K), unemployment rose to 4.2%, and wage growth slowed to 0.1% m/m. Odds of an October Fed hike have faded to about 20%, but the 10-year yield is near 5.3% and markets still price more tightening by year-end. 🏦
🌏 Asian markets
🇯🇵 Nikkei 225 is up about 2.1% at around 69,700 (intraday), near a three-month high on AI and chip stocks
🇭🇰 Hang Seng is down about 0.5% at around 23,850 (intraday), after Friday's 2.6% drop to 23,972
🇦🇺 ASX 200 is higher, led by banks and miners
🇨🇳 🇰🇷 China is closed for Golden Week (back October 8), and South Korea is closed for a national holiday
🇺🇸 Wall Street (Friday close)
📈 S&P 500: 7,722.72 (+0.73%)
📈 Nasdaq 100: 30,807.93 (+1.00%), a record close
📈 Dow: +0.49%
💱 Forex
💵 The dollar index is near 102.4, its highest since April 2025
🇪🇺 EUR/USD is trading around 1.12, near its lowest since May 2025, as the French–German bond spread widens to about 130 bps (the widest since 2012) and Spanish political risk adds pressure
🇯🇵 USD/JPY is holding near 158 despite firmer rhetoric from Japanese officials
🛢 Oil
Brent is near $101.5, slightly lower, pressured by the 100M-barrel G7 stock release and recovering Gulf exports. Middle East risks remain, including the Houthi conflict in Yemen. Saudi Aramco also cut its November Arab Light price to Asia by $3, the widest discount since June 2020.
🥇 Gold
Gold is steady near $4,140, down about 6% over the past month as high yields cap gains. Support is at $4,110, with resistance in the $4,230 area. 🔎
₿ Crypto
Bitcoin is holding around $86,000 and Ethereum is around $2,700. 🪙
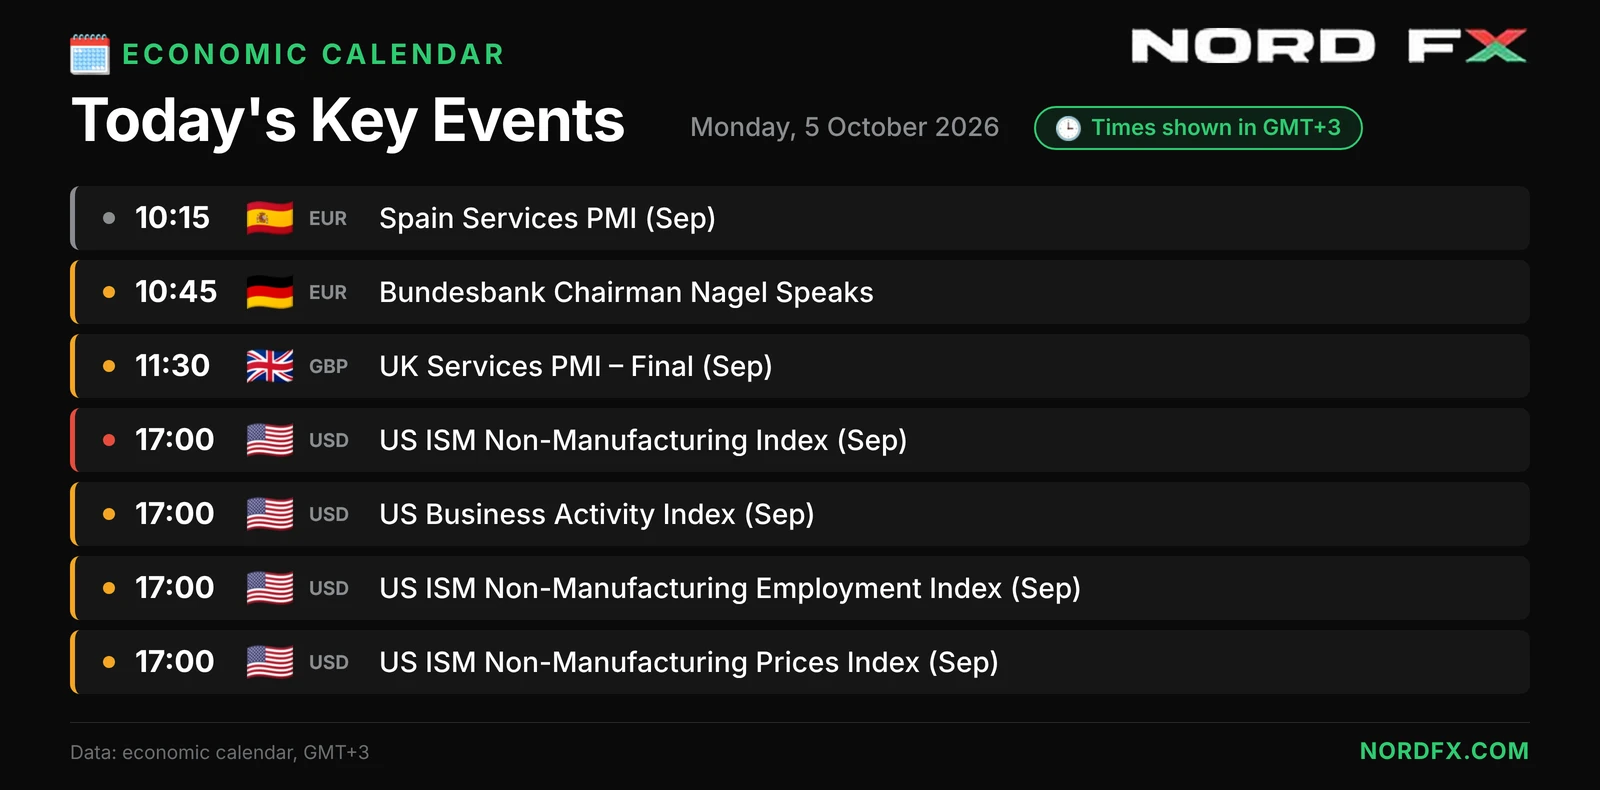
🗓 Today's calendar (GMT+3)
⏰ 16:45 – US S&P Global Services PMI
⏰ 17:00 – US ISM Services PMI (Sept): forecast 55.1, prior 55.4
📌 Later this week: FOMC minutes on Wednesday at 21:00, jobless claims and the ECB accounts on Thursday, and Canadian jobs data on Friday
🎯 Trade smart with NordFX! 🚀
Go Back Go Back
